
Article
The FTC Safeguards Rule: who it covers and what it requires
The FTC Safeguards Rule requires non-banking financial institutions to protect customer data. Find out if your business is covered and what you need to do.
- PROTECT
6 min ·
INDUSTRY / MORTGAGE & LENDING
A borrower who doesn't hear back in minutes calls the next lender on the list, and a closing that slips a day can cost the whole deal. At the same time, loan files carry exactly the kind of financial data wire fraud crews are after, and closing is the moment they attack. Cyber6 helps you respond faster, chase documents without wearing out your processors, and keep every closing wire where it belongs.
5 min read
Inbox
From: new-wiring-instructions@titlecl0sing.com
URGENT: revised wire details for your closing
Hi, our bank changed its receiving account after an internal update.
Please use the new wiring instructions attached and confirm once sent.
The sender address new-wiring-instructions@titlecl0sing.com looks like a real supplier but is spelled differently: titlecl0sing.com.
WE GET IT
A lead comes in and waits
A rate quote request lands at 9 PM. The borrower hears back the next morning from your team, and from three other lenders overnight.
The document chase never ends
A processor sends the same request for pay stubs and bank statements three times. The file sits in stipulation while the borrower forgets to reply.
Closing day slips
One missing signature or condition pushes closing by a day. The rate lock, the moving truck, and the seller's patience are all on the line.
The wire instructions that looked right
A borrower gets an email that looks like it's from the title company, with new wiring instructions for their down payment. It's not from the title company.
Loan officers on personal phones and email
A loan officer texts a borrower's Social Security number from a personal phone because it's faster than logging into the loan origination system.
Rate drops and nobody calls past clients
Rates fall and a stack of past clients could refinance today, but nobody has time to work that list before a competitor does.
A shared inbox for borrower documents
Pay stubs, W-2s, and bank statements arrive as email attachments into a shared inbox, sitting there long after they should be encrypted or deleted.
A processor juggling forty files
Each file needs the same follow-up: check what's missing, ask for it, chase it again. There's no time left to catch the file that's actually stuck.
THE IMPACT
Deals lost to slower response
In lending, the first call back usually gets the application. Every hour of delay is a chance for the borrower to lock in with someone else.
Closings that fall through
A slipped closing date can cost the deal entirely, along with the loan officer's time and the referral relationship with the agent.
A borrower's down payment, gone
Wire fraud at closing routes a borrower's funds to a criminal's account. It is very hard to recover and can end the transaction and the client relationship.
A breach notification under GLBA
Loan files hold Social Security numbers, tax returns, and bank statements. A breach can require notifying every affected borrower and your state regulator.
Processor hours spent chasing, not closing
Time spent re-requesting the same documents is time not spent moving files that are ready to close.
COMPLIANCE
This is general information, not legal advice.
THE FIX
AUTOMATE
The right customers find you on Google, AI search, and social, in your own voice.
Every call, text, form, and quote turns into booked work.
Speed-to-lead
Every inquiry gets an immediate response with a way to schedule a call, day or night, and a loan officer is notified right away.
Customers hear from you at the right time, without your team chasing them.
Rate-change and past-client outreach
Past clients get automatic, timely outreach when rates move in their favor, with an easy way to start a new application.
Money you've already earned comes in sooner, without awkward phone calls.
Less retyping and waiting, more time for the work that matters.
Document chase
Borrowers get automatic reminders for exactly what's missing, with a simple upload link, and processors get a short list of files actually stuck.
PROTECT
We put a required callback step in place for any wiring instructions, using a phone number from a source other than the email itself, before any funds move.
What this means for you: A spoofed email asking for new wire details can't move a borrower's money.
Borrowers upload pay stubs, W-2s, and bank statements through an encrypted portal instead of emailing sensitive documents back and forth.
What this means for you: Financial documents don't sit unprotected in an inbox waiting to be found.
We filter for lookalike domains and flag any message that introduces new payment or wire instructions, right when borrowers are most likely to fall for it.
What this means for you: The message that looks like it's from the title company gets caught before the borrower acts on it.
Loan officers and processors log into the loan origination system and email with , not just a password.
What this means for you: A stolen password isn't enough to reach a borrower's loan file.
We back up loan files and pipeline data, keep copies isolated from ransomware, and test that restores actually work.
What this means for you: A ransomware attack doesn't stop closings that are already scheduled.
EMPOWER
Loan officers and processors
Short, regular sessions on phishing, business email compromise, and safe handling of borrower financial documents.
Borrowers, delivered by your team
Simple materials your team sends every borrower explaining how wire fraud at closing works and exactly how to verify instructions before sending money.
Loan officers and marketing staff
What borrower information can and can't go into AI tools, and how to use them for drafting communications without exposing financial data.
A DAY WITH CYBER6
7:00 AMAUTOMATE
An overnight rate inquiry already received an automatic reply, and the loan officer sees it flagged first thing.
10:15 AMAUTOMATE
A processor's list shows exactly which three files are stuck waiting on documents, out of forty open loans.
1:40 PMPROTECT
An email claiming to be from a title company with new wire instructions is flagged and held for phone verification before anyone acts on it.
3:00 PMEMPOWER
A loan officer double-checks a borrower's wire instructions by phone before closing, because the borrower education email reminded them to ask.
YOUR TOOLS
We work alongside the systems you already use. We'll confirm what connects during your assessment.
QUESTIONS
The goal is an immediate automatic response, typically within a minute, followed by a loan officer reaching out personally as soon as possible after.
Yes. We work alongside these systems and confirm exactly what connects during the assessment.
We can still receive and secure what comes in by email, but we set up the portal so it's the easier, faster option for most borrowers.
It adds a short phone call, not a delay to the closing date. It happens well before funds are scheduled to move.
Yes, the rule applies regardless of size, though the required program scales with your risk and complexity.
Yes. We can work alongside your current IT vendor on security and automation, or take over fully, and we'll coordinate so nothing falls through.
Nothing. It's a free review of your lead response time and wire security, with a written summary of what to fix first.
RESOURCES
The FTC Safeguards Rule requires non-banking financial institutions to protect customer data. Find out if your business is covered and what you need to do.
6 min ·
The Gramm-Leach-Bliley Act requires financial institutions to explain their information-sharing practices and protect sensitive data. Learn the basics for your firm.
6 min ·
Your lead response time is often the difference between a new customer and a lost opportunity. Learn how to use automation to ensure you're always the first to reply.
6 min ·
Every result is measured against your own starting point.
How we prove it →PART OF ONE PARTNER
Protect · IT & Cybersecurity
IT and cybersecurity, managed around the clock.
You're here
Empower · Training for Businesses & Individuals
Training that builds skills for your team and your career.
Explore EmpowerWHY CYBER6
One partner, not three vendors
The people automating your work also run and protect your IT and train your team, so nothing falls between companies.
Plain language and real people
You talk to people who explain things clearly, answer the phone, and tell you what they'd do in your place.
Measured against your own numbers
We record where you start before anything changes, then report results against that baseline.
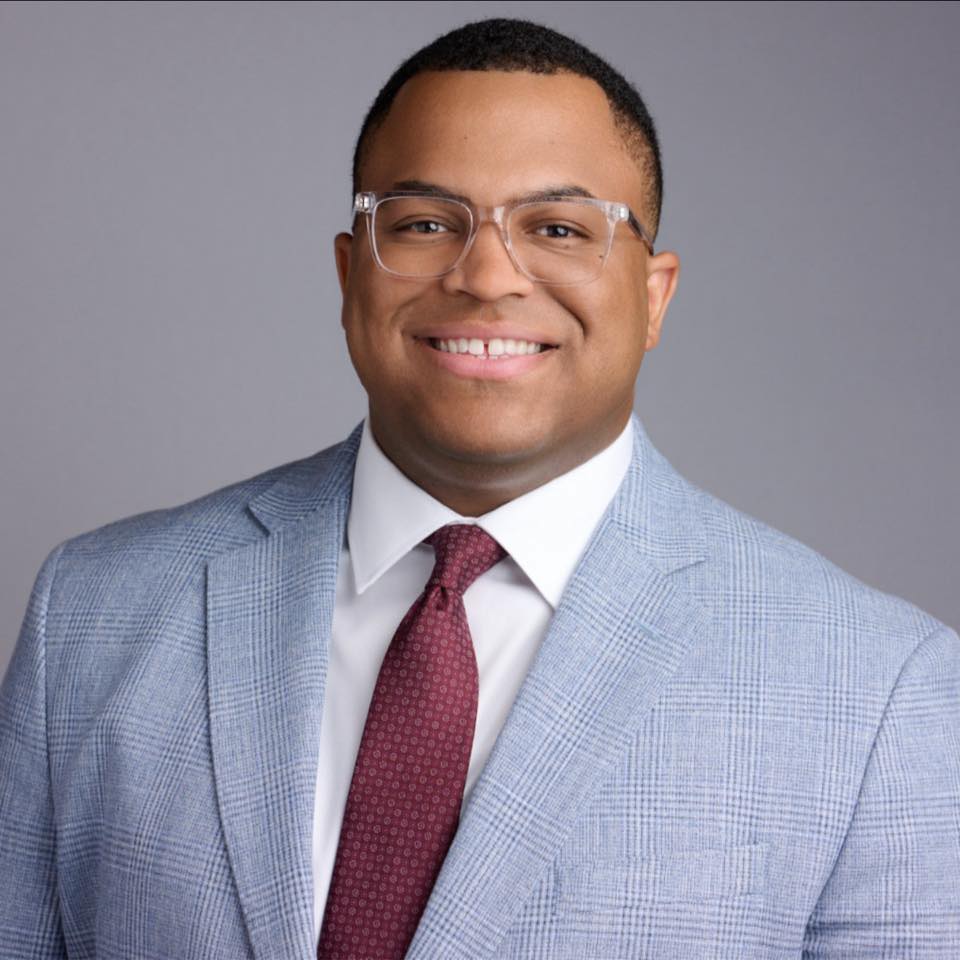
Marquis Carroll, Founder & CEO. Marquis has spent years doing hands-on IT and security work through his own business, and runs a mentorship program that has helped people start careers in tech.
Our storyGETTING STARTED
Explore
A relaxed 30-minute conversation about how your business runs and what's getting in the way. No cost, no pressure.
You get: honest answers on whether we can help.
Assess
We look at your systems, security, manual work, and training needs, and record your starting numbers.
You get: a plain-English picture of your risks and opportunities.
Set up
A prioritized plan and proposal, then a kickoff that introduces your team and sets up access safely.
You get: a shared timeline and who to call for what.
Enable
We roll out in phases, train your team, and walk you through your first results.
You get: your first plain-English report, measured with PROVE.
A 30-minute call. No cost, no pressure, and honest answers.